
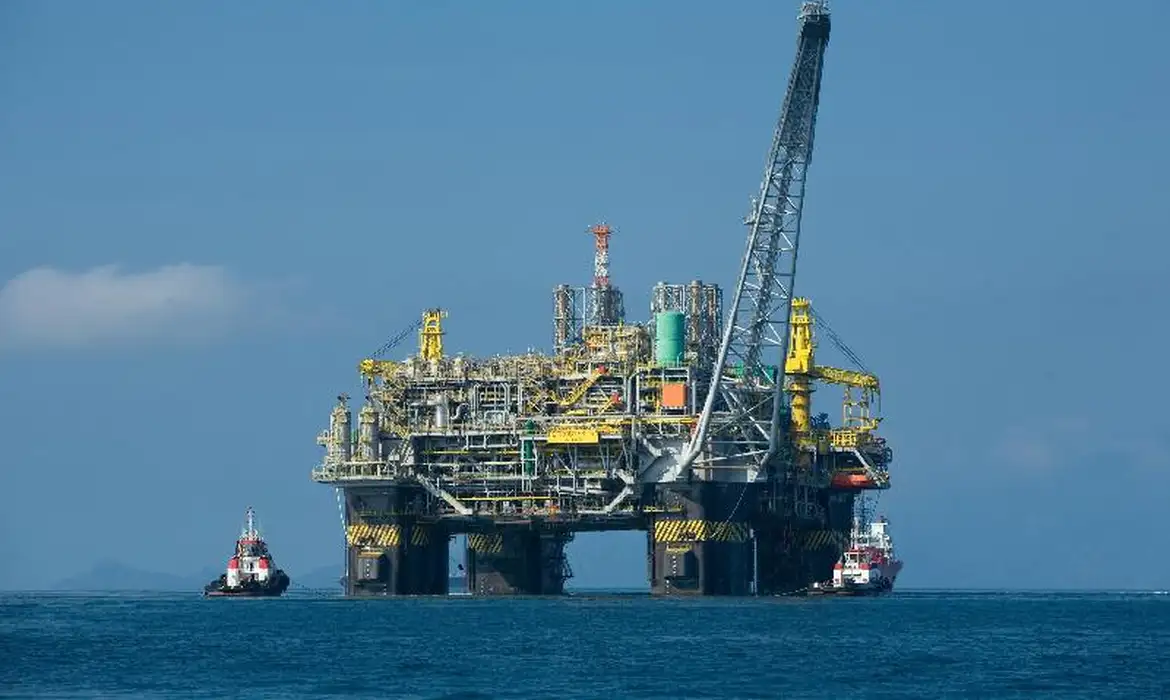
A 3ª Turma da Câmara Superior declarou a nulidade de auto de infração contra a Petro Rio Jaguar Petróleo S.A. por entender que a fiscalização não seguiu o procedimento adequado para questionar o regime aduaneiro já concedido à empresa. O caso envolve cerca de R$ 18 bilhões em valores atualizados e trata de supostas irregularidades relacionadas ao Repetro-Sped.
The majority of the panel followed the vote of the rapporteur, council member Tatiana Belisário. According to her, the tax authorities presented arguments related to the requirements for granting the regime, but formalized the charge as resulting from non-compliance with the conditions of use.
Belisário argued that if the intention was to revoke the Repetro-Sped concession, it would be necessary to follow the procedure for reviewing or revoking the concession act, and not simply issue a notice to collect the suspended taxes.
A relatora também apontou que a falta de clareza comprometeu o direito de defesa da contribuinte, já que não era possível identificar com precisão se a fiscalização pretendia revisar a concessão do regime ou apurar irregularidades em sua utilização. O voto restabelece, nesse ponto, a conclusão da Delegacia de Julgamento (DRJ) pela nulidade do lançamento, com fundamento no artigo 59, inciso II, do Decreto 70.235/1972 .
The company's defense argued that the tax authorities initiated the procedure and directly issued the infraction notice, without prior notification to correct or clarify alleged errors or to present the administrative appeal provided for in the regulations of the regime at the time of the events.
“A Câmara Superior reconheceu que exigir R$ 17 bilhões sem esclarecer sequer o que se pretendia (rever a concessão ou apurar descumprimento) cerceia a defesa do contribuinte e torna nulo o lançamento. O caso da PetroRio, portanto, além de um absurdo jurídico, é emblemático, pois materializa o compromisso do Carf com a higidez das normas e procedimentos da Receita Federal”, afirmou o advogado Eduardo Kiralyhegy, do NMK Advogados, ao JOTA .
The expert on the case, tax lawyer Leonardo Branco, from Daniel, Diniz e Branco – Advocacia Tributária e Aduaneira, classified the process as "quite peculiar" and highlighted that the tax authorities, when re-analyzing the Repetro requirements during the migration to Repetro-Sped, should have followed the review procedure foreseen in the legislation to cancel or disregard the special regime. Branco also stated that, a few weeks after the assessment was issued, the responsible auditor left the Federal Revenue Service.
In the hearing, the Treasury, represented by attorney Fabrício Sarmanho de Albuquerque, expressed dissatisfaction with the fact that the discussion regarding the nature of the defect had not been fully addressed, due to the lack of an "ancillary appeal" in the administrative process. Belisário agreed with the criticism and pointed out the need for adjustments to the regulations.
Council member Vinícius Guimarães was outvoted, having voted to deny the company's appeal on its merits. Previously, Guimarães had voted against considering the appeal.
Colegiado : 3ª Turma da Câmara Superior
Process : 10730.726286/2022-80
Parts : Petro Rio Jaguar Petróleo S.A. e Fazenda Nacional
Relatora : Tatiana Belisário
Source: JOTA